Russia’s ability to sustain high-intensity offensive operations is no longer limited by political will or frontline manpower, but by the physical limits of its industrial base. For the past four years, the Russian state has performed a feat of economic mobilisation that surprised the West. However, the period of rapid expansion through the refurbishment of Soviet stockpiles and triple-shift labour is over. The machine has begun to eat itself. We are now witnessing a terminal shift in Russian tactical objectives, driven not by a change in intent, but by the cold reality of industrial exhaustion.
The Ceiling of Mobilisation
The Russian economy is currently operating at near-total capacity. Unemployment has hovered at record lows for years, creating a chronic labour deficit that pits the defence sector against the civilian economy. While the Kremlin has successfully insulated the population from the worst effects of sanctions through aggressive state spending, this spending is now the primary driver of an inflationary spiral that even high interest rates cannot tame. The incentive structure has shifted: the state can no longer afford to simply outspend the problem without risking structural collapse.
Crucially, the Russian military-industrial complex has exhausted the "easy" gains of the 2022-2025 period. During those years, production spikes were achieved by rehabilitating thousands of stored T-72 and T-80 tanks. Those reserves are now depleted or consist of hulls too degraded for modern utility. Future production must rely on new builds, which require advanced machine tools, high-end semiconductors, and specialised ball bearings—all of which remain under heavy sanction pressure or depend on fragile Chinese supply chains.
The Attrition of the Machine
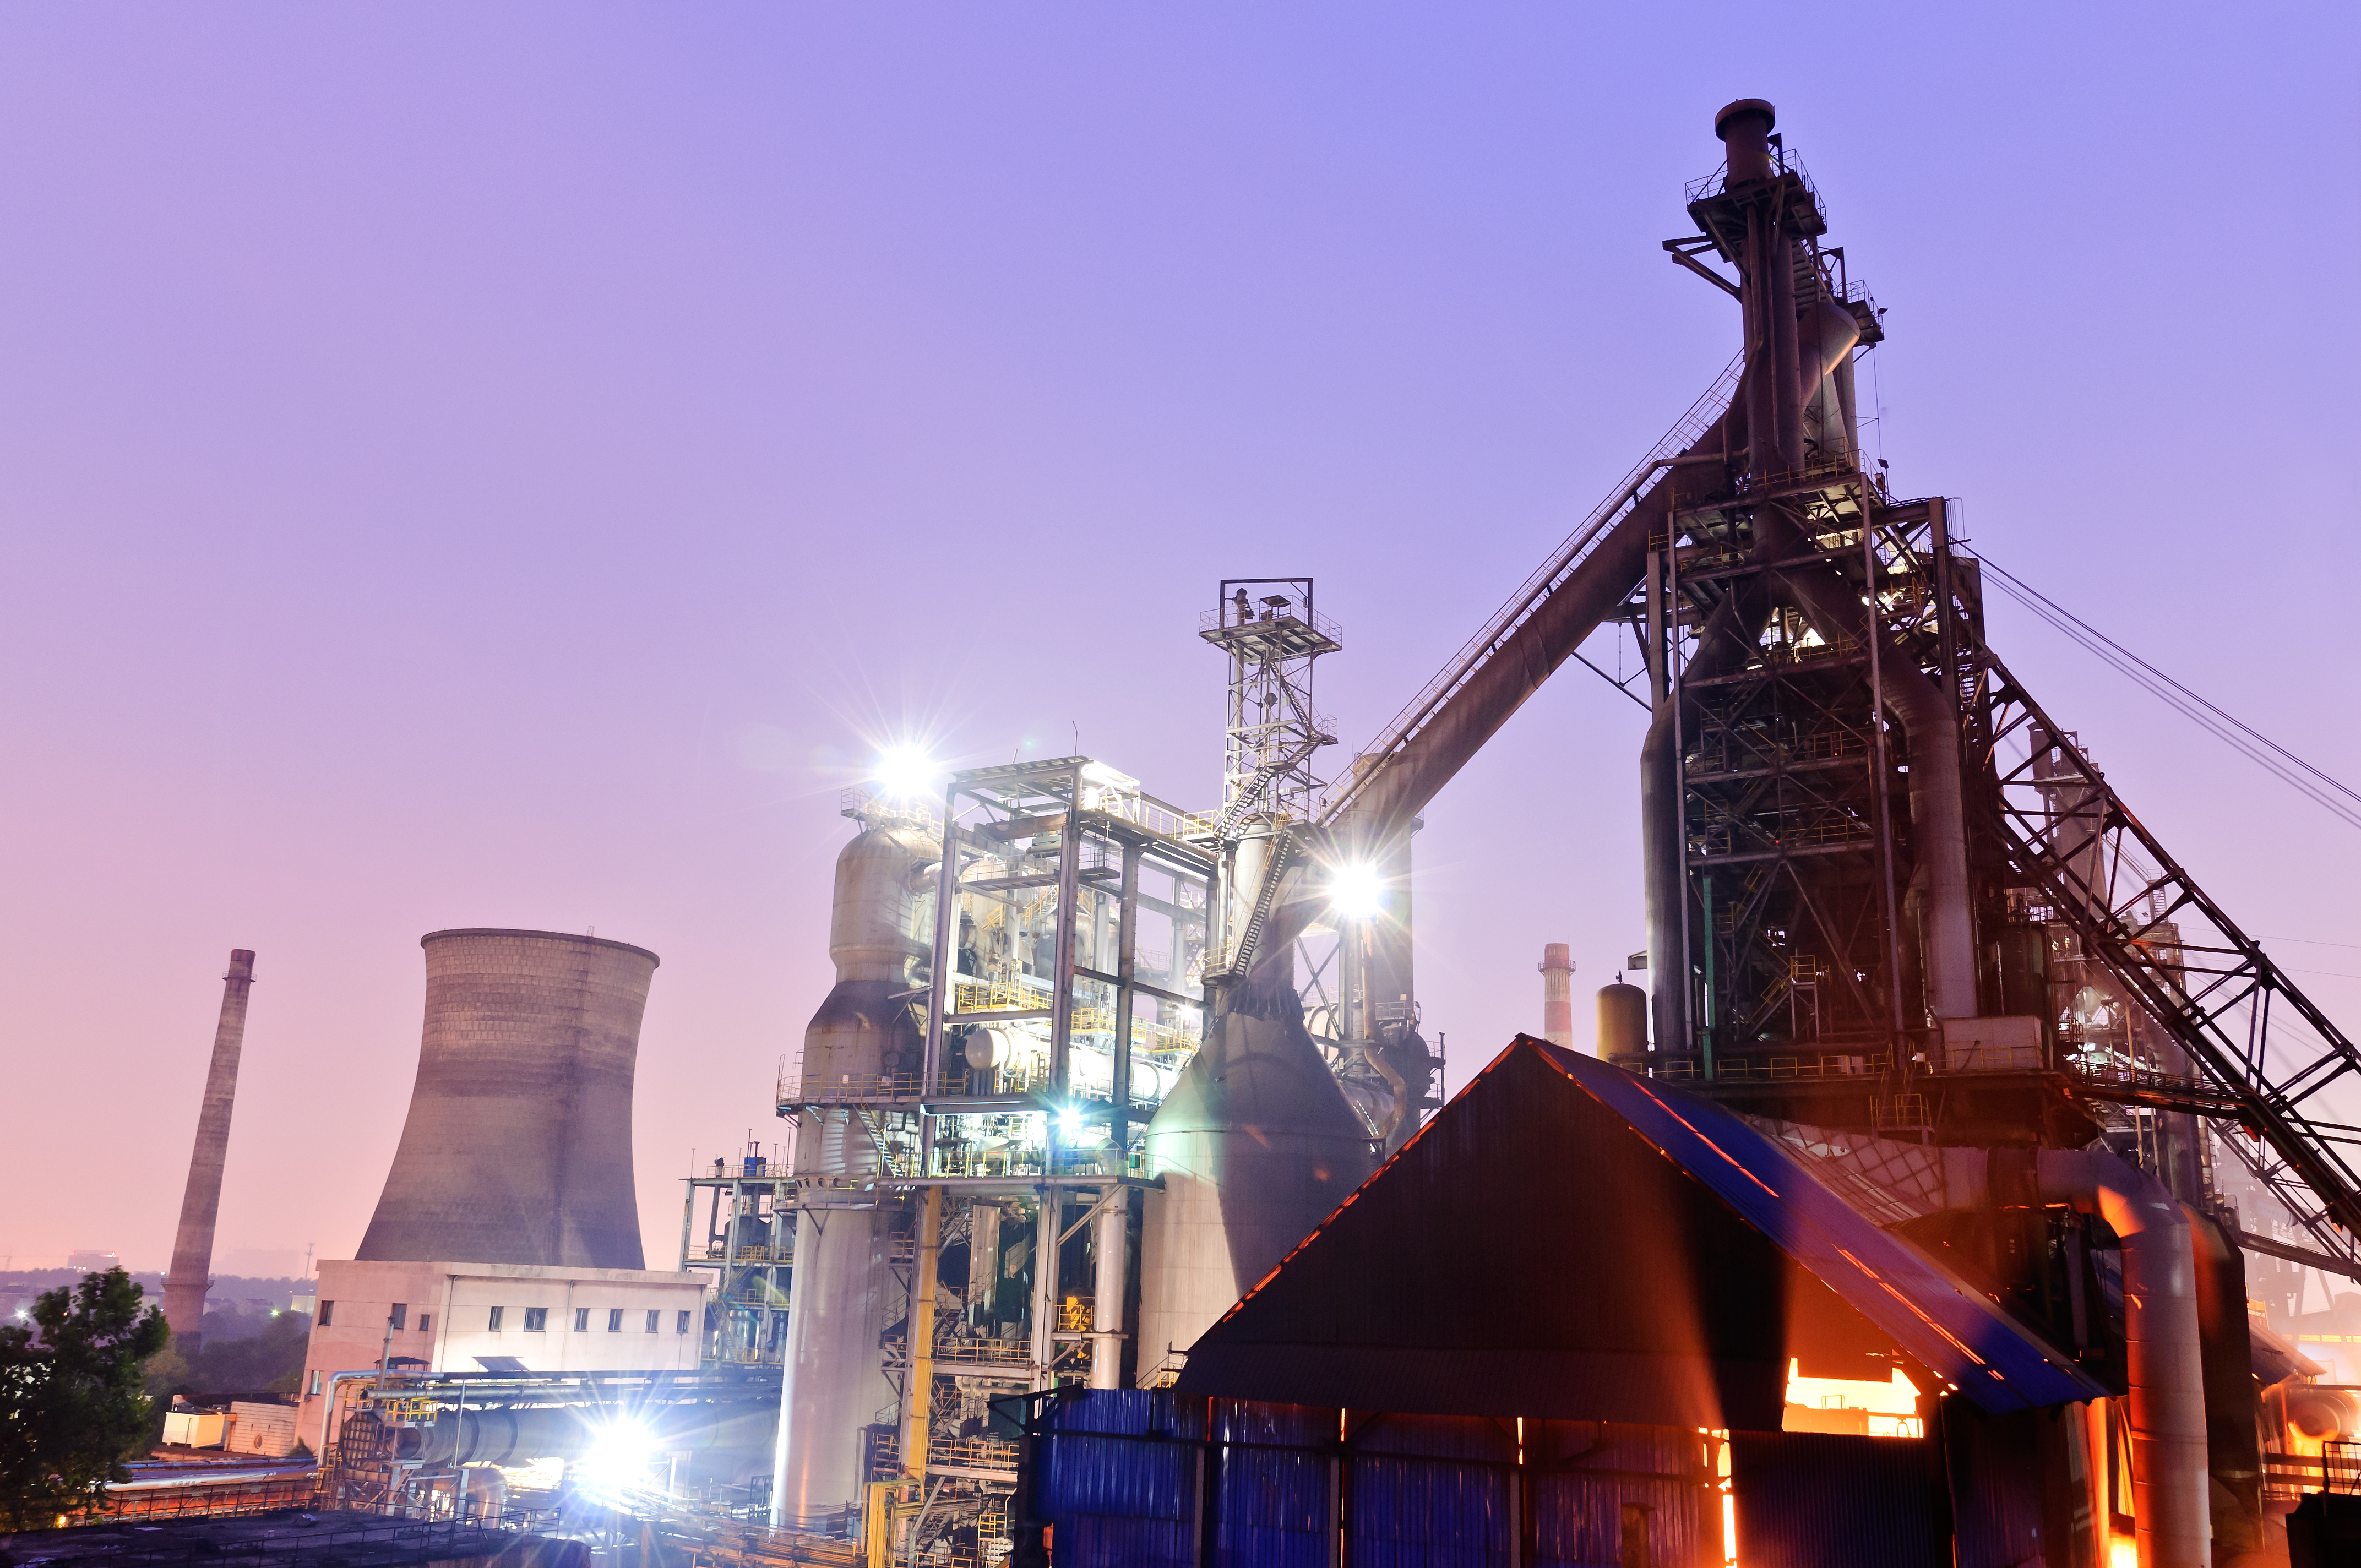
Industrial exhaustion is not just about producing fewer shells; it is about the degradation of the means of production. Factory floor machinery in the Urals and Siberia has been running at 24-hour capacity for years without scheduled maintenance. The second-order effect is a rising rate of industrial accidents and a sharp drop in precision. When a machine tool designed for a ten-year lifespan is burnt out in three, the replacement cost is not just financial, but temporal. Russia cannot simply buy time; it is running out of hardware durability.
This creates a paradox for the Russian General Staff. To keep the army supplied for a perpetual war of attrition, they must slow down the rate of consumption. This explains the recent shift toward localised, low-intensity grinding rather than the large-scale armoured breakthroughs attempted in the war’s earlier phases. The goal is no longer to win quickly, but to avoid losing the capacity to fight at all.
A Historical Parallel: The German Hindenburg Programme
In 1916, Imperial Germany launched the Hindenburg Programme, an ambitious plan to double munitions production. On paper, it was a success; output soared. In reality, it hollowed out the German domestic economy, diverted all skilled labour away from sustainable sectors, and created a rigid industrial structure that could not adapt when the strategic situation changed. Like Russia today, Germany mistook industrial output for economic strength. When the collapse came, it was not the front line that broke first, but the industrial and social machinery behind it. The Kremlin is currently walking this same narrow path, trading future economic viability for immediate kinetic output.
What Most People Miss
The common narrative focuses on Russia’s ability to bypass sanctions through third countries. What this ignores is the "complexity tax." Importing a high-end CNC machine via Kyrgyzstan or the UAE increases the cost by 300% and the lead time by months. More importantly, these machines lack the official software updates and technical support required for precision manufacturing. Russia is increasingly relying on a "Frankenstein" industrial model—patching together disparate technologies that lack interoperability. This leads to a hidden decline in the quality of Russian ordnance. They are firing more, but hitting less accurately, requiring even more shells to achieve the same tactical result. It is a cycle of diminishing returns.
Strategic Consequences
The primary consequence of this industrial ceiling is a shift in Moscow’s diplomatic posture. Russia is now incentivised to seek a "frozen" conflict—not because it wants peace, but because it needs to reset its industrial clock. A ceasefire that allows for the continued occupation of current territories while pausing the consumption of heavy hardware would be a strategic victory for the Kremlin. It would allow them to retool their factories and wait for Western political resolve to fracture further.
Conversely, for Ukraine and its allies, this suggests that the window of maximum Russian vulnerability is approaching. If the West can maintain or increase the cost of Russian procurement while the Ural factories continue to overheat, the Russian military’s ability to hold ground may degrade faster than their ability to replenish it. The war has moved from a contest of maps to a contest of maintenance cycles.
What to Watch
- Interest Rate Hikes: If the Russian Central Bank continues to push rates toward 20% or higher, it is a clear signal that the civilian economy is being sacrificed to prevent total industrial overheating.
- Chinese Dual-Use Exports: Any slowdown or restriction in the flow of high-end Chinese machine tools will be more damaging to Russia than any number of new frontline battalions.
- The Tank Gap: Monitor the ratio of newly manufactured T-90Ms to refurbished T-62s on the battlefield. A rising percentage of the latter indicates the exhaustion of the mid-tier reserve.
- Railway Logistics: Increased reports of rolling stock failure within Russia will signal that the heavy transport infrastructure is succumbing to the same wear-and-tear as the factories.
KJ Verdict
Russia is not running out of money, but it is running out of friction-less industrial capacity. The pivot we are seeing is a forced adaptation to physical limits. The Kremlin is now playing a game of tactical preservation, attempting to secure its gains before the internal costs of the war become existential. The risk for the West is misinterpreting this slowdown as a sign of defeat rather than a strategic recalibration. Russia is not stopping; it is downshifting to avoid an engine blowout. Whether it can successfully cool the machine without the entire structure seizing up remains the defining question of the next eighteen months.